This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
Super Central Bank Week in Focus: Fed & BoJ Take Center Stage
Super Central Bank Week in Focus: Fed & BoJ Take Center Stage
Ultima Markets Weekly Market Insights – 14–18 September 2026
Global financial markets are entering one of the most critical trading windows of the year as the Federal Reserve (Fed), Bank of Japan (BoJ), and Bank of England (BoE) deliver their policy decisions in a dense “Super Central Bank Week.”
Following elevated U.S. Producer Price Index (PPI) and Consumer Price Index (CPI) prints last week—compounded by $105 crude oil—the global monetary policy path is tightening sharply, raising fears of seasonal market turmoil often termed the “September Effect”.
Central Bank Tightening, More to Come?
With 3 major central banks on queue this week, the Bank of England is widely expected to hold, but the market will focus on the forward guidance from the BoE. However, the main focus this week will be more on the Federal Reserve and the Bank of Japan.
Bank of England (BoE): Vote Split to Frame Tone
The BoE is broadly expected to keep interest rates unchanged. Market focus will center on the Monetary Policy Committee (MPC) vote distribution—with a 3-0-6 vote split anticipated—and whether any hawkish dissents emerge to alter Cable’s trajectory.
Federal Reserve (Fed): 25 bps Hike Base Case, Focus Shifts to Inflation Stance
Money markets have firmly priced in a 25 basis point rate hike at this week’s FOMC meeting, with CME FedWatch probabilities currently sitting at 86% and expected to approach 100% as the announcement nears. With a rate hike largely discounted, market participants will focus entirely on forward guidance.
While Fed officials, particularly Fed Chair Warsh, who explicitly stated they will not provide any forward guidance, may refrain from committing to an explicit future policy path, any aggressive emphasis on persistent inflation risks will prompt money markets to price in an additional hike before the end of 2026, providing strong fundamental backing for the Greenback.
Bank of Japan: Rate Hike Expected, Tightening Commitment in Spotlight
Meanwhile, the BoJ is widely expected to deliver a policy rate hike as domestic wage growth and secondary energy inflation pressure price stability. The key variable will be whether BoJ Governor Kazuo Ueda commits to further monetary tightening through late 2026 or signals a terminal pause, which will dictate near-term Yen dynamics.
Weekly Macro & Technical Outlook
U.S. Dollar Index (USDX): Rebound Potential Hinges on Hawkish Inflation Stance
The Greenback stabilized late last week as rate hike expectations solidified following elevated inflation releases.
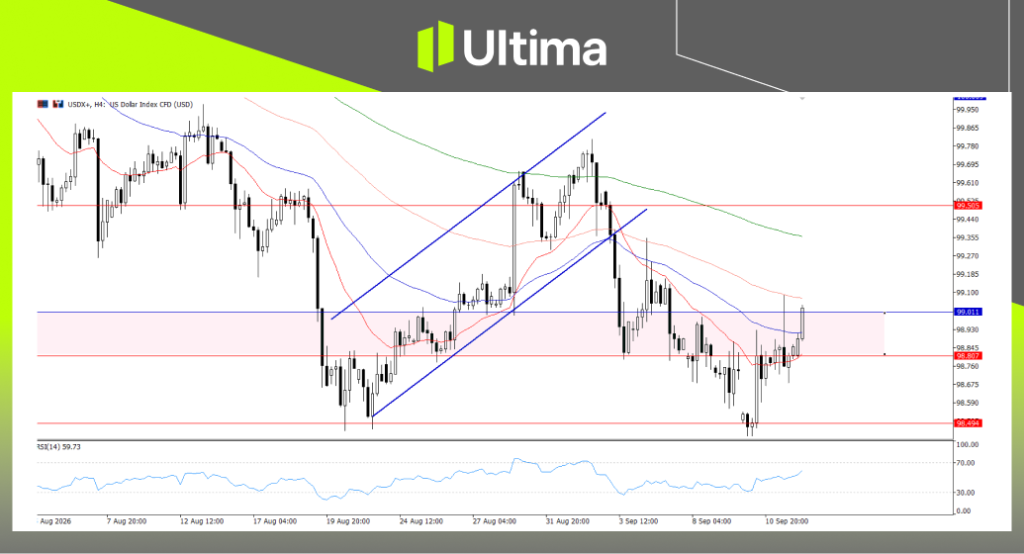
USDX, H4 Chart Chart | Ultima Markets MT5
USDX found support above 99.00 again following last week’s CPI data, supported by rising Treasury yields and hawkish Fed repricing. With the U.S. Dollar now reclaiming territory above 99.00, this shift may alter the Dollar Index’s near-term bearish outlook into a potential bullish reversal.
Holding above 99.00, if supported by a hawkish post-meeting Fed stance following the September decision, could see the Dollar edge higher toward the 99.50 – 100.00 zone again.
Conversely, if the Fed delivers a “dovish hike” without highlighting further inflation risks, USDX risks falling back toward the 98.00 support baseline.
USD/JPY: High-Stakes Divergence Between Fed & BoJ
The currency pair faces two-way volatility as policy rate announcements from both central banks land in close proximity.
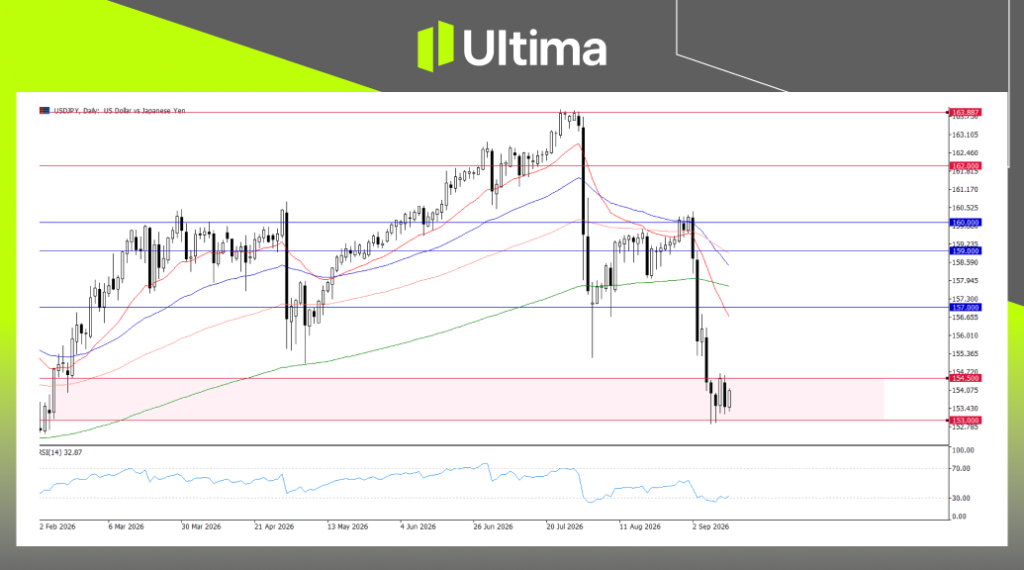
USDJPY, Daily Chart | Ultima Markets MT5
USD/JPY remains locked in a high-volatility corridor between 153.00 and 154.50 following the sharp sell-off earlier.
While a hawkish BoJ could bolster the Yen to extend its gains against the Dollar, the primary driving force may ultimately shift back to the Fed. If we see a hawkish Fed, USD/JPY could regain upward momentum, where technically reclaiming above the 154.50 area would confirm a broader recovery in USD/JPY.
Meanwhile, if we see a hawkish BoJ hike paired with a cautious (less hawkish) Fed, it could spark a sharp downside repricing toward fresh lows, especially if price action breaks below the major support at 153.00.
U.S. Equities (NAS100 / SP500): Seasonal Fragility Under Rate Hike Pressure
Equity benchmarks face severe structural headwinds as discount rates rise alongside energy inputs.
Focus should remain heavily on the Nasdaq 100 index if we see a hawkish shift and synchronized tightening across global central banks, where tech-heavy valuations face heightened pressure.
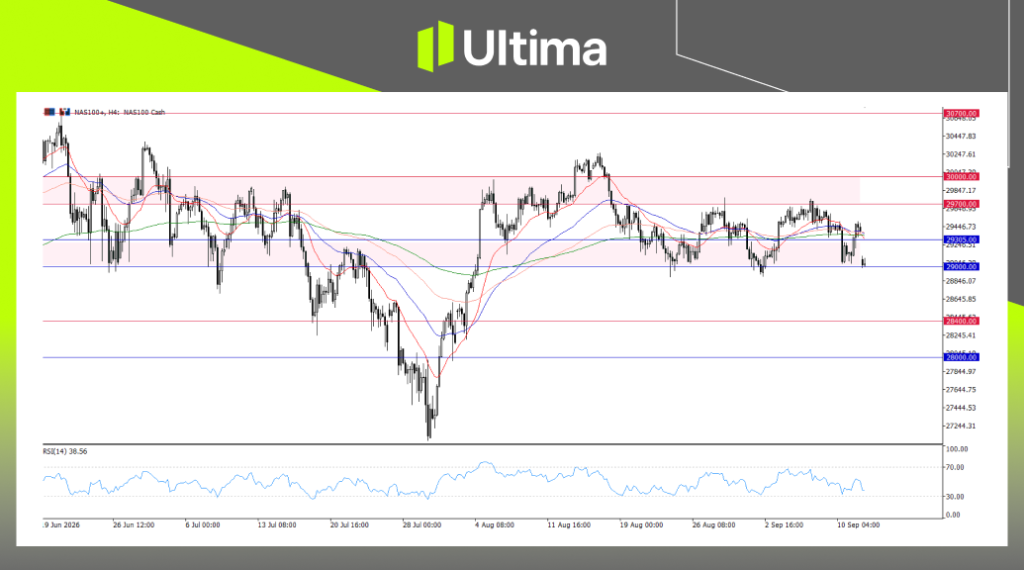
NAS100, H4 Chart | Ultima Markets MT5
NAS100 is hovering near the fragile 29,000 technical floor (while SP500 tests critical support at 7,600).
If Super Central Bank Week confirms further global tightening, a breakdown below 29,000 on NAS100 could trigger accelerating sell-offs toward 28,000 – 28,400, confirming seasonal “September Effect” weakness across broad equity markets.
Market Summary & Key Highlights This Week
Synchronized central bank tightening and stubborn inflation metrics create a high-volatility environment, with policy stances setting the macro tone for Q4—or at least for September, as traders eagerly observe whether the “September Effect” curse returns.
What to Watch This Week:
FOMC Rate Decision & Statement (Wednesday): Watch for confirmation of the 25 bps hike and inspect policy statements for hawkish commentary on 2026 inflation risks.
BoJ Rate Decision & Press Conference (Friday): Monitor whether Governor Ueda commits to further rate hikes or signals a policy pause.
BoE MPC Vote Split (Thursday): Track whether the vote matches the 3-0-6 expectation or shifts hawkish.
Key Technical Levels: Monitor USDX at 99.00, USD/JPY at 152.00/148.00, and NAS100 at the 29,000 support floor.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.